A defensible, audit-ready record of how clearly you communicate across a mortgage relationship that can last decades.
boards must review, at least annually, whether their firm is delivering good outcomes for retail customers, including whether customers understand what they are told.
the FCA’s Mortgages and Home Finance: Conduct of Business sourcebook sets out what lenders must tell customers, and when, from illustrations and offer documents to arrears and payment shortfall information.
for mortgage lenders, that test runs across offers and illustrations, product transfer and end-of-deal letters, arrears notices and changes to terms.
the same expectation applies whether you are a high-street lender, a building society or a specialist lender.
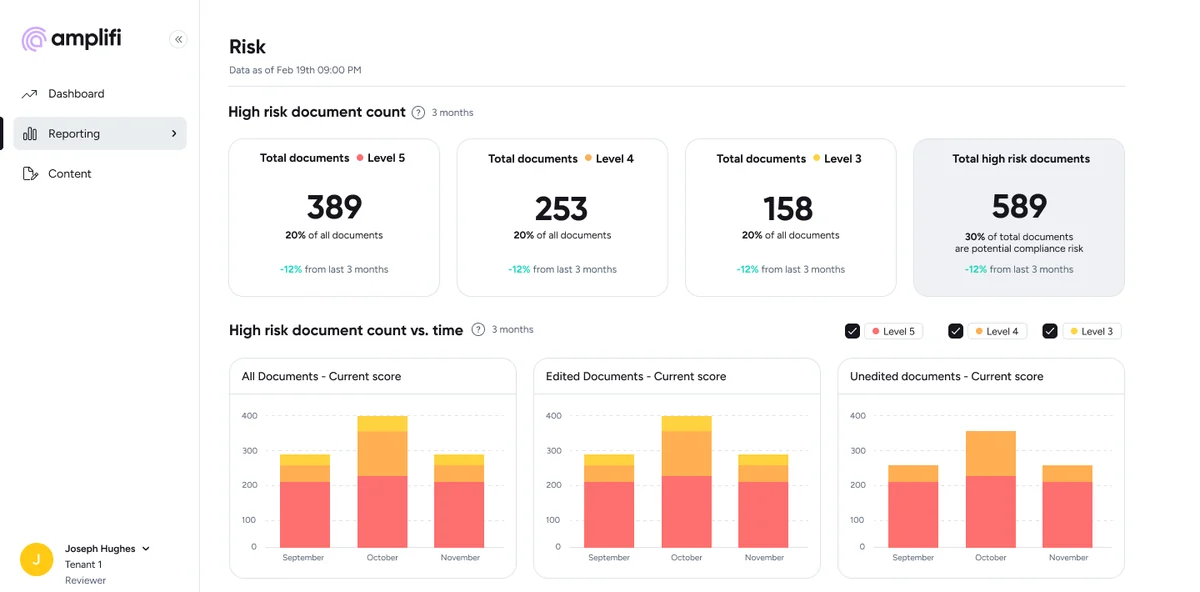
Score offers, illustrations, arrears notices and changes to terms in one place.
See where comprehension risk peaks as customers make big decisions.
Every score and review is logged, ready for the annual Consumer Duty review.
Through FinTech Scotland’s Financial Regulation Innovation Lab, we’re helping financial services firms adopt AI responsibly while meeting regulatory expectations.
the Responsible AI Innovation Call (Q3 to Q4 2026) looked for new ways for firms to use AI responsibly within the rules.
we worked with 13 global financial and professional services firms, including Lloyds Banking Group, M&G, NatWest, PwC and Sopra Steria, to understand their AI challenges and their reporting and governance needs.
we were awarded a £50,000 grant to create sector-wide benchmarks for consumer understanding, through a publicly available intelligibility score.