Whether it’s a credit card, a loan, Buy Now Pay Later or an overdraft, Amplifi shows whether borrowers could understand what they signed, and gives you the evidence to prove it.
lenders must give borrowers pre-contract information and adequate explanations, so they can judge whether a product meets their needs and what it will cost them.
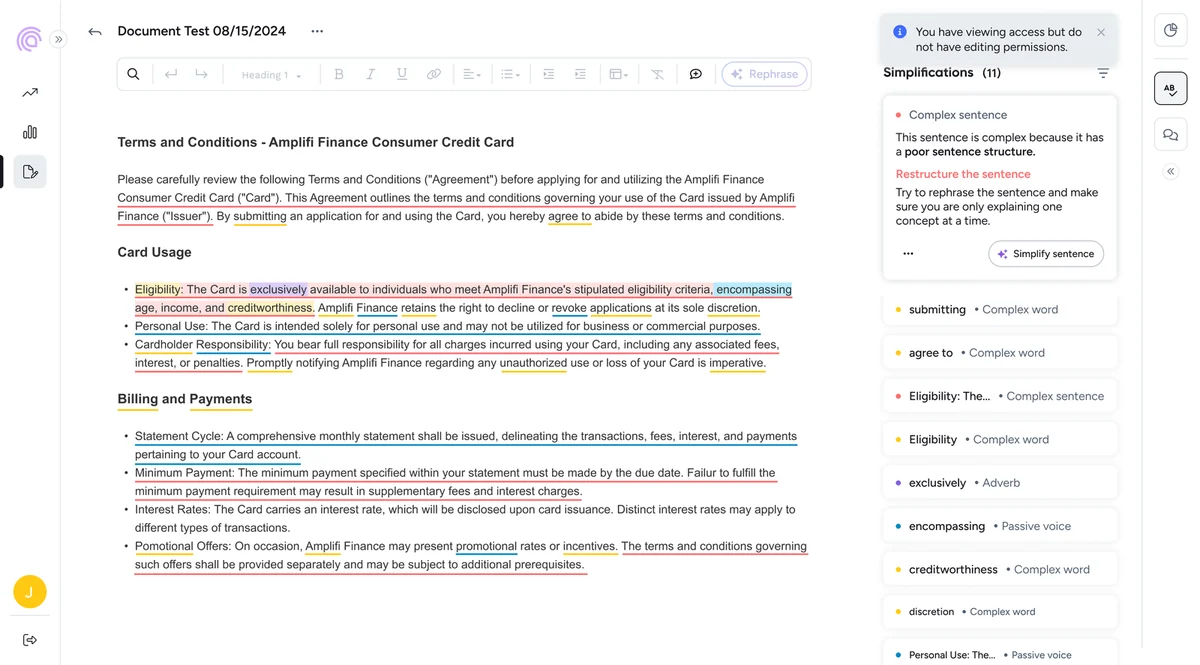
turns those requirements into a test of real understanding. Firms must show their communications equip customers to make effective decisions, not just that the right information was sent.
since 6 April 2025, the CMA can enforce consumer law directly, including the Consumer Credit Act, and fine firms up to 10% of global turnover.
Test agreements, pre-contract information and explanations before they reach borrowers.
Pinpoint the terms most likely to be misread, and simplify them.
Every score and change is logged, ready for your board or a regulator.

Inside the FCA’s Regulatory Sandbox, we showed prescribed credit documents can be made clearer without breaking the rules.
68 → 89
PCI intelligibility score
Fair For You, an FCA-regulated Community Interest Company lending to vulnerable and thin-filed customers, found its prescribed Pre-Contract Credit Information (PCI) and Default Notice left many customers confused, anxious and unsure where to find help.
with the Gillmore Centre at Warwick Business School and Nottingham University, we produced simplified and digital layered versions that kept all the prescribed content. We tested them with 318 people online and 20 people using eye-tracking.
the PCI’s intelligibility score rose from 68 to 89, taking reach from 72% to over 90% of UK adults. The Default Notice rose from 75 to 84, taking reach from 82% to over 90%. Readers of the simplified notice were more likely to believe help was available, and to say they would make contact.
FCA Regulatory Sandbox
In 2023 we live-tested simplified Pre-Contract Credit Information and Default Notices with a regulated lender in the FCA’s Regulatory Sandbox. That evidence informed HM Treasury’s Consumer Credit Act Reform Phase 1 consultation (May 2025), and its case for reform in chapter 2.

HM Treasury, CCA Reform consultation, para 2.4
HMT considers that some of the key issues with the CCA include:
Prescriptive, confusing and duplicative: For example, some of the existing disclosure requirements can be confusing for consumers (e.g. statutory references in documents such as the credit agreement and technical legal language in pre-contract information, arrears and default notices), potentially leading to poor outcomes for consumers. Some provisions require excessive prescription, duplicative information and a rigid approach, preventing firms from adapting information and journeys to consumers’ needs.
Through FinTech Scotland’s Financial Regulation Innovation Lab, we’re helping financial services firms adopt AI responsibly while meeting regulatory expectations.
the Responsible AI Innovation Call (Q3 to Q4 2026) looked for new ways for firms to use AI responsibly within the rules.
we worked with 13 global financial and professional services firms, including Lloyds Banking Group, M&G, NatWest, PwC and Sopra Steria, to understand their AI challenges and their reporting and governance needs.
we were awarded a £50,000 grant to create sector-wide benchmarks for consumer understanding, through a publicly available intelligibility score.