Clarity you can prove. Compliance you can track.

We believe clarity in communication isn’t a nice-to-have, it’s a compliance requirement. We built Amplifi to help firms deliver intelligible, measurable, and regulator-ready communications.
Our partners
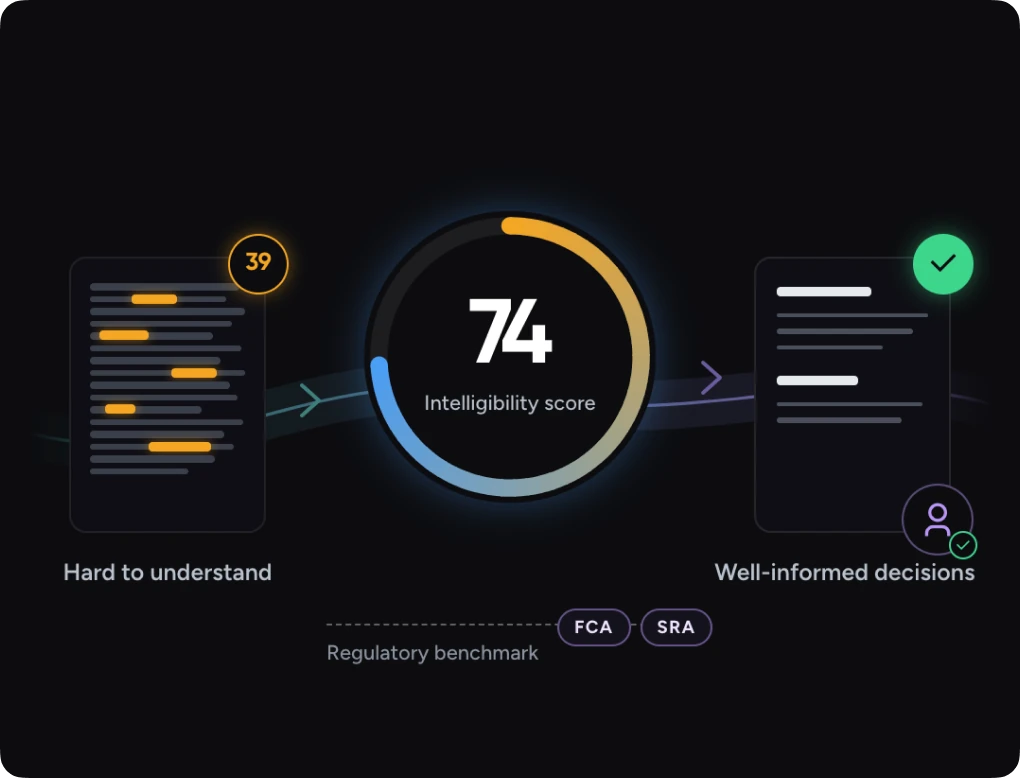
A hard-to-understand document is scored for intelligibility against the FCA and SRA benchmark, leading to well-informed decisions

Why Intelligibility Matters?

Intelligibility is the most accurate predictor of understanding, providing regulators like the Financial Conduct Authority (FCA) and Solicitors Regulation Authority (SRA) with a quantifiable benchmark, ensuring financial and legal communications are clear, effective, and support well-informed decision-making.

Built for the way your sector is regulated

Every regulator asks the same question in its own language: did the customer understand? Here’s why firms in each of our core sectors need Amplifi to answer it.

Legal

Clear enough to be enforceable.

Consumer Rights Act
CMA37 unfair terms guidance
Consumer Credit Act
Consumer Duty
How Amplifi helps

Amplifi turns the fairness test into an objective, evidence-based score: a live drafting tool for your practice and a client service you can offer.

Illustration for Amplifi's Legal solution
Why it matters

The Consumer Rights Act, the CMA’s guidance on unfair contract terms (CMA37) and the Consumer Credit Act all turn on the same test: can a typical consumer reasonably understand the term they’re agreeing to? For law firms and in-house teams serving financial services, that test now sits alongside the Consumer Duty’s expectations on consumer understanding.

Credit

Communications all borrowers can understand.

Consumer Credit Act
Consumer Duty
DMCC Act
How Amplifi helps

Amplifi scores your credit agreements, pre-contract information and customer communications for comprehension risk, giving you evidence that borrowers could understand what they signed.

Illustration for Amplifi's Credit solution
Why it matters

Whether it’s a credit card, a loan or an overdraft, the Consumer Credit Act and the FCA’s consumer credit rules require lenders to give borrowers information and explanations they can use to judge whether the product is right for them. The Consumer Duty turns that into a test of real understanding, and the DMCC Act gives the CMA direct powers to fine firms for breaching consumer law.

Mortgages

Clarity for the biggest financial commitment most customers make.

FCA Consumer Duty
How Amplifi helps

Amplifi scores and evidences intelligibility across your mortgage communications, giving your board a defensible, audit-ready record, whether you are a high-street lender, a building society or a specialist lender.

Illustration for Amplifi's Mortgages solution
Why it matters

The FCA’s Consumer Duty requires boards to review, at least annually, whether their firm is delivering good outcomes for retail customers, including whether customers understand what they are told. For mortgage lenders, that test runs across a relationship that can last decades: offers and illustrations, product transfer and end-of-deal letters, arrears notices and changes to terms.

Investment & savings

Prove the risk was understood, not just disclosed.

FCA Consumer Duty
PRA rules
Consumer Composite Investments (CCI)
How Amplifi helps

Amplifi gives compliance and financial promotions teams an objective, regulator-ready score for every disclosure, promotion and customer communication: the same benchmark the FCA used to assess 172 pre-sale investment disclosure documents.

Illustration for Amplifi's Investment and savings solution
Why it matters

From savings accounts and ISAs to pensions and consumer composite investment products, the FCA’s Consumer Duty asks firms to show their communications support informed decisions. Where providers are dual-regulated, PRA rules add disclosure requirements, such as depositor protection information for savers. And the Consumer Composite Investments (CCI) regime raises the bar on how clearly costs and risk are communicated to retail investors.

Payments

Clear at the speed of checkout.

Payment Services Regulations 2017
Electronic Money Regulations 2011
Consumer Duty
How Amplifi helps

Amplifi scores your terms, disclosures and in-journey messaging for comprehension risk, at the volume and pace payment firms operate.

Illustration for Amplifi's Payments solution
Why it matters

Payment journeys are short and decisions are made in seconds, so terms have to land first time. The Payment Services Regulations 2017 require payment firms to give customers information in easily understandable words and in a clear, comprehensible form, and the Electronic Money Regulations 2011 bring e-money issuers under the same oversight. Both are supervised by the FCA, whose Consumer Duty asks payment and e-money firms to show customers genuinely understand what they are told.

Debt

Clarity for customers who need it most.

FCA Consumer Duty
DMCC Act
How Amplifi helps

Amplifi scores every arrears letter, notice and payment plan for comprehension risk, so you can show customers in difficulty were given information they could understand and act on.

Illustration for Amplifi's Debt solution
Why it matters

Customers in financial difficulty are often the most vulnerable people that lenders, collectors and debt advice organisations serve. The FCA’s Consumer Duty expects collections, arrears and debt advice communications to be understood by the people who receive them, and the DMCC Act now lets the CMA fine firms directly for breaching consumer law.

Credit Unions
TBC

Lending and saving your members can understand.

PRA
FCA Consumer Duty
How Amplifi helps

Amplifi gives credit unions a ready-made way to score, simplify and evidence member communications, so you can show members were given information they could understand.

Graphic placeholder: Credit Unions
Custom illustration, 16:9. To be designed.
Why it matters

Credit unions can be dual-regulated by the PRA and the FCA, and the FCA’s Consumer Duty can apply to how they communicate with members about loans, savings and changes to their accounts. With lean compliance teams, building an intelligibility testing programme from scratch is rarely realistic.

Gambling
TBC

Plain language is a licence condition.

Gambling Commission LCCP
CMA unfair terms guidance
DMCC Act
How Amplifi helps

Amplifi scores and monitors your terms, promotions and player communications against that standard, flagging high-risk language before it reaches players.

Graphic placeholder: Gambling
Custom illustration, 16:9. To be designed.
Why it matters

The Gambling Commission’s LCCP requires terms and player-facing communications to be set out in plain and intelligible language. Alongside it, the CMA’s guidance on unfair terms and its direct enforcement powers under the DMCC Act raise the cost of terms players cannot reasonably understand.

Amplifi Turns Regulatory Risk into Measurable Assurance for Legal and Regulatory Compliance

Everything your team needs to assess,
improve, and govern communications

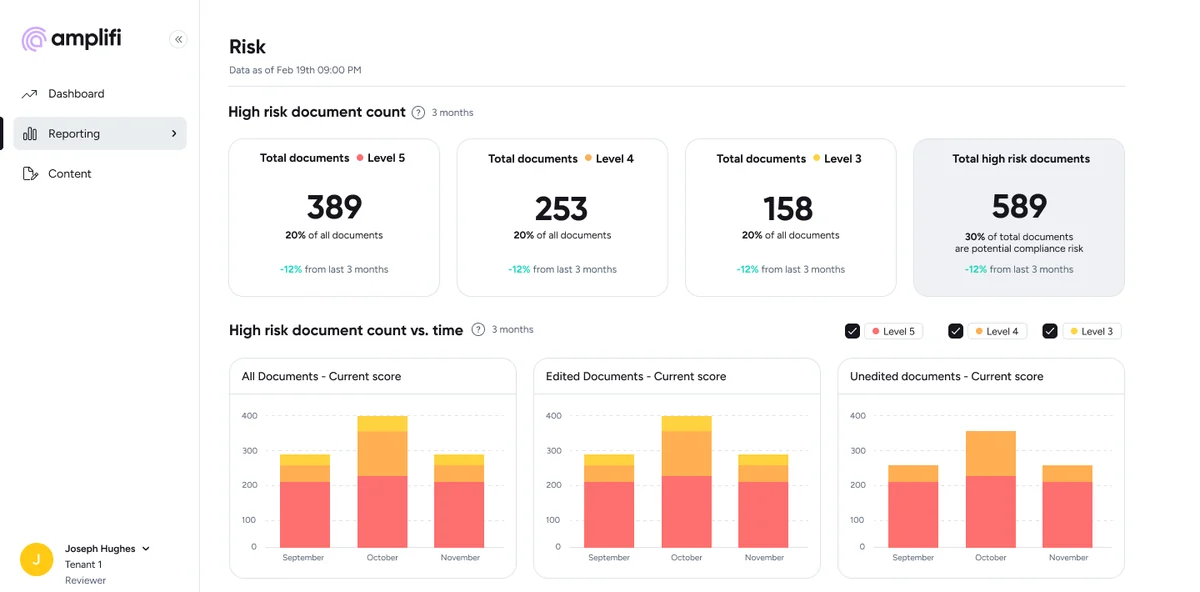
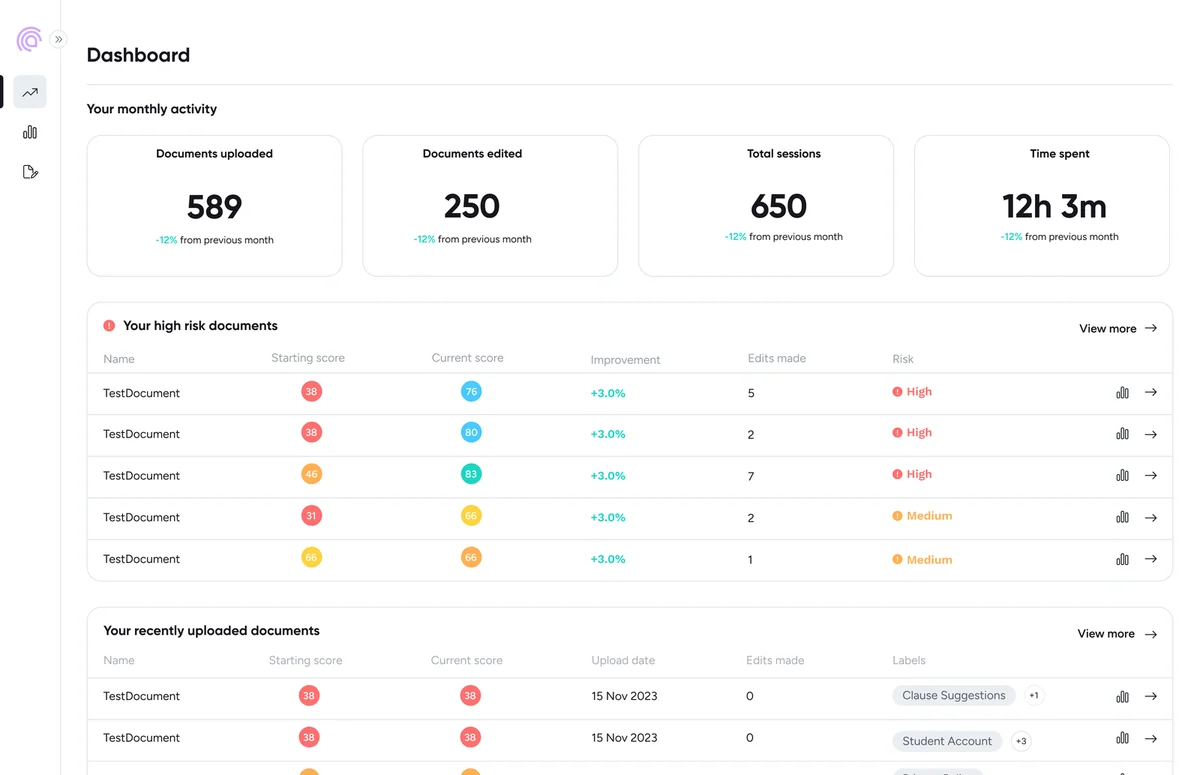
Amplifi was built to address the regulatory challenge. Using our AI model to assess, score, and evidence clarity at scale. So you can focus on delivering communications that not only tick boxes, but actually work.
Test Your Comms at Scale

Benchmark and Reduce Risk

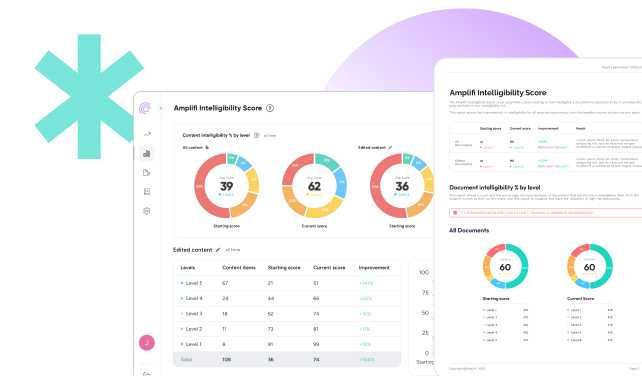
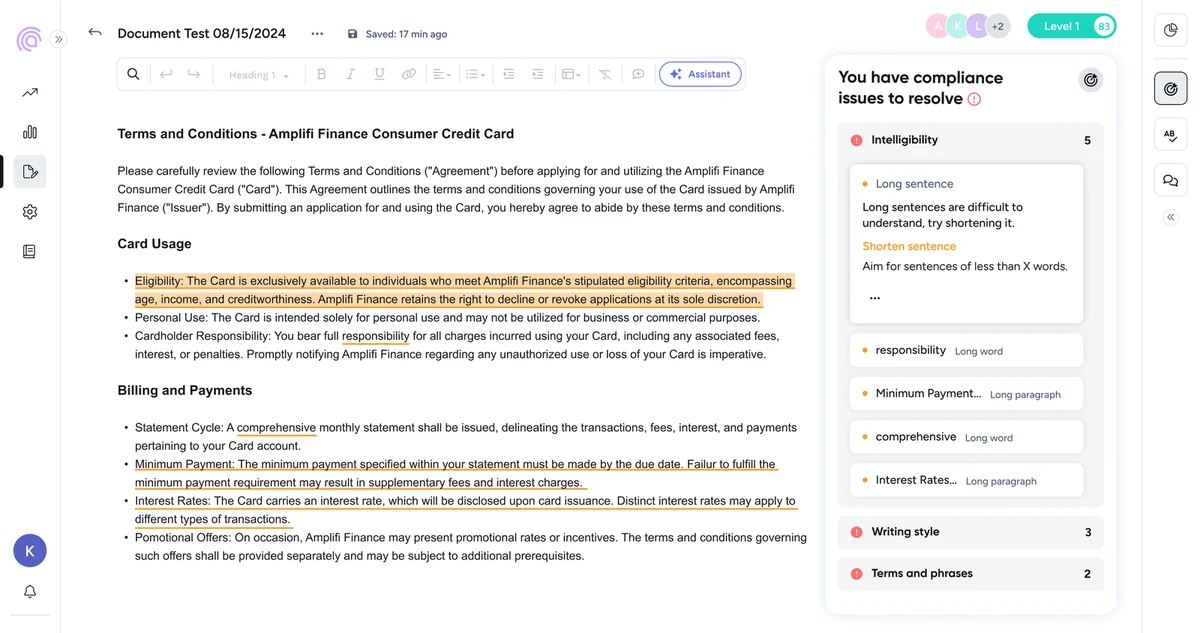
Amplifi’s Intelligibility Risk Score identifies high-risk communications, prioritising documents to reduce compliance risks and improve clarity across your business.
Set Governance Targets & Rules

Smarter AI Content Compliance

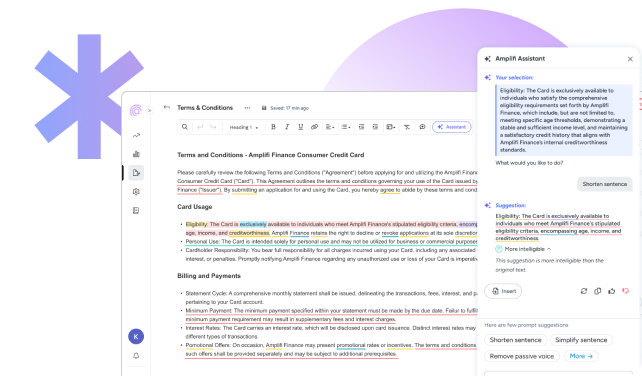
Automate risk detection, standardise terms, enforce writing rules, and embed brand governance directly into your workflow.
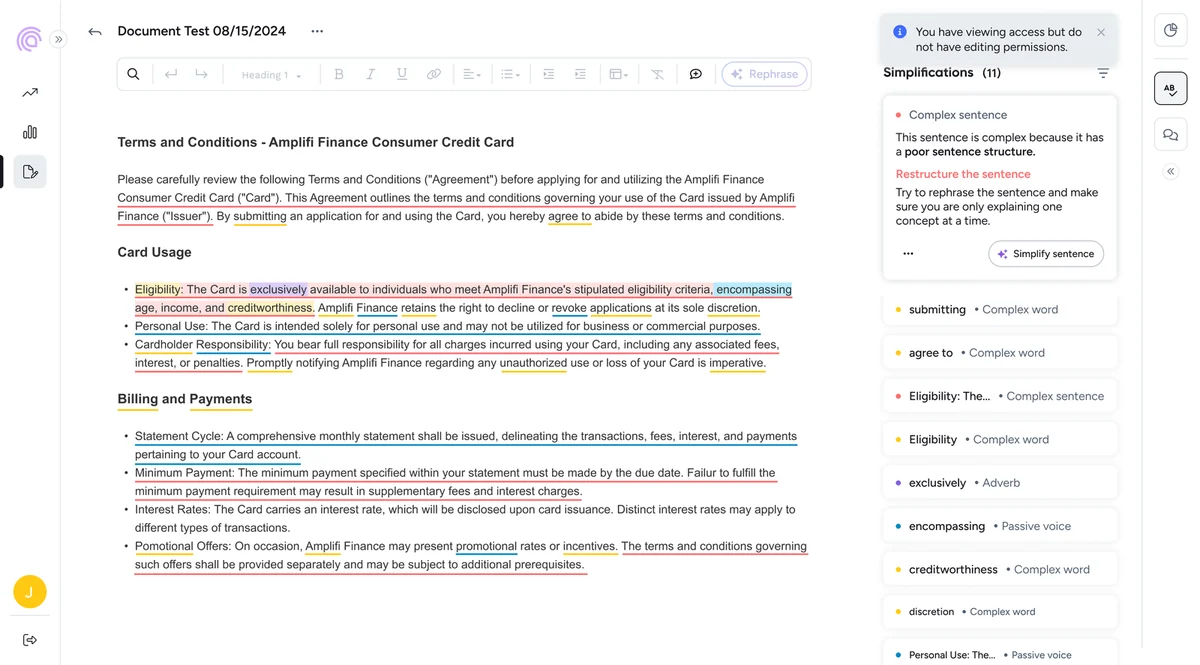
Efficient & Targeted Simplification

Improve Critical Communications

Visualise risk, get AI-guided clarity improvements, and streamline editing for consumer- and regulator-focused content.
Streamline the Review Process

Compliance, Simplified

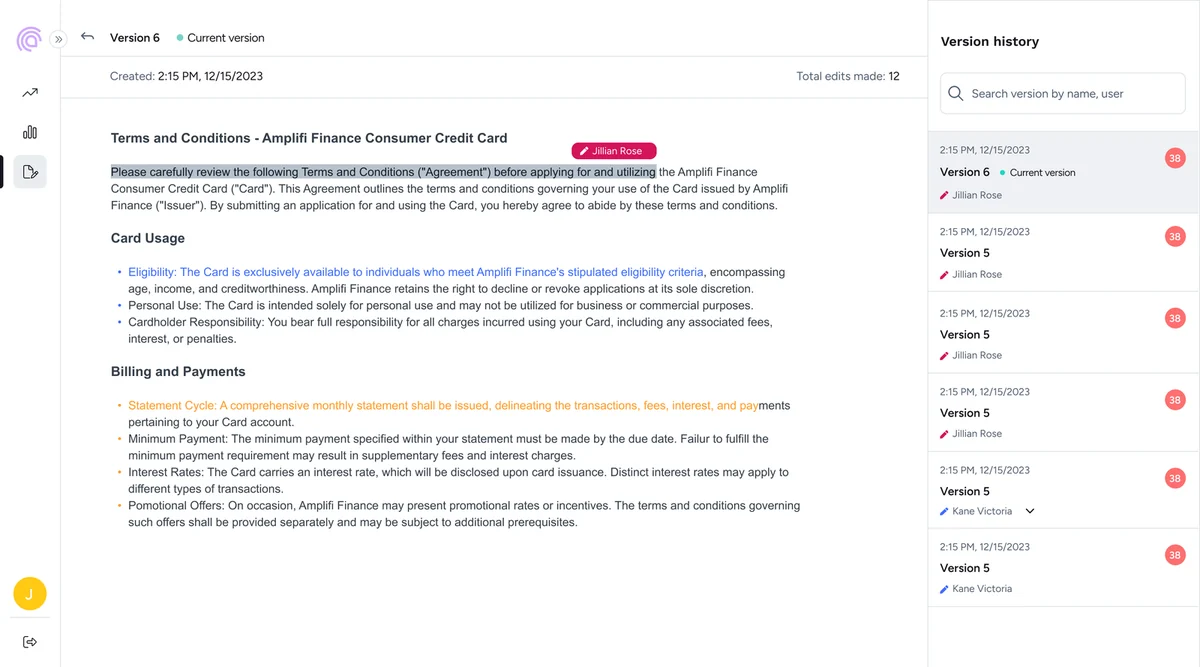
Collaborate, track intelligibility, embed approvals, and maintain accountability to meet compliance and quality goals efficiently.
Create Regulator Ready Reports

Validate consumer outcomes

Monitor content clarity and compliance risks to generate audit-ready, defensible evidence. Prove to regulators that your comms prevent foreseeable harm.

Enterprise Security & Control

Built for high-stakes communications in regulated environments.

Deterministic models

A consistent, reliable intelligibility score every time.

Role & team based Access Control

Precise team permissions.

ISO 27001 Security

Independently audited protection.

No AI Model Training

Your data is never used to train AI models.

Full Audit Logs

Complete activity visibility.

Data residency

All data is retained in the UK or EU, never transferred to the US.

Mandatory MFA

Secured access point defense.

Tenant Isolation

Total client data separation.

FSQS registered

Trusted supplier in financial services sector.

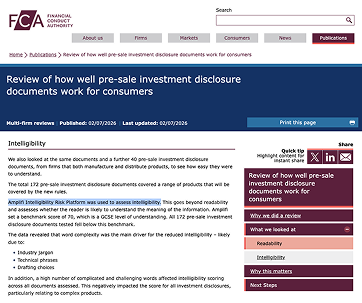
The FCA use Amplifi to benchmark the investment market.

The FCA used Amplifi to test 172 pre-sale investment disclosure documents for intelligibility.
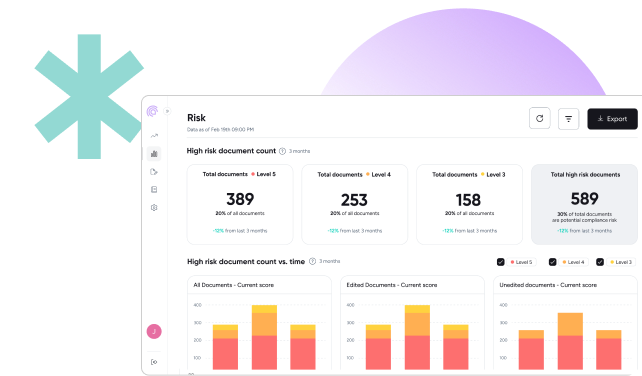
The results set a sector benchmark ahead of new CCI rules in 2027. This signals what good and bad disclosure looks like. Expect more studies across credit cards, debt, and legal agreements.
Let's talk

Still have a question?
Get in touch.

Whether you’re ready to explore Amplifi, looking for a demo or just want to understand how it fits into your workflow, we’re here to help.